BUSINESS & FINANCE
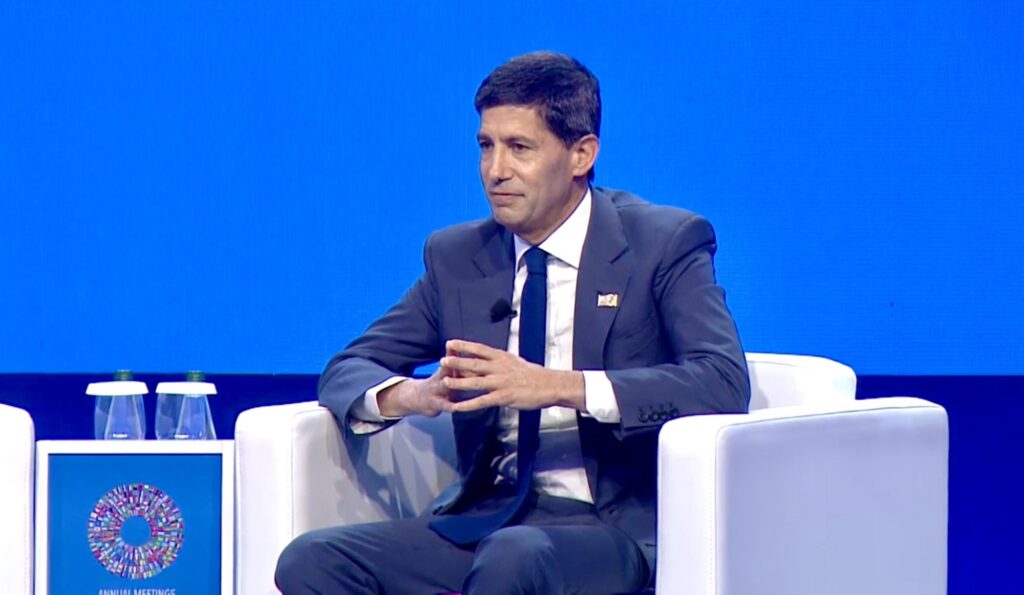
Bob Dylan’s The Times They Are A-Changin’ offers an apt soundtrack for Kevin Warsh‘s emerging vision of the Federal Reserve. Five months into his tenure as chair, Warsh is moving to change how the central bank communicates monetary policy, reviews the economy and sets aside time for longer-term questions about its role.
It’s a pivot less about promising that change will come than accepting that the economy itself is changing quickly, and constantly and need a monetary policy that can adapt to those changes, instantly. Warsh has questioned the Fed’s reliance on forward guidance, which uses policy statements and signals about the likely path of interest rates to shape market expectations. He wants the central bank to leave more room for decisions to reflect incoming data rather than what policymakers have said at earlier meetings.
His announcement Wednesday that the Federal Open Market Committee will reserve meetings for broader monetary policy discussions is the latest step in that direction. The Fed will continue to meet eight times a year, but one meeting in 2027 will focus exclusively on strategy, without a vote on interest rates or an expected policy statement. In 2028, Warsh expects two strategy meetings and six meetings devoted to setting policy.
The plan follows five task forces Warsh announced in June to examine the Fed’s communications, balance sheet, data, productivity and jobs, and inflation framework. The groups are expected to offer recommendations on areas Warsh believes warrant a fresh look.
These changes are taking shape as the Fed weighs strong economic growth against inflation that remains above its 2% target and a global economy experiencing whiplashes. At his latest press conference, Warsh described an economy expanding faster than earlier estimates suggested, with consumer spending and business investment holding up. Higher energy prices, meanwhile, have added another complication to the inflation outlook.
Here are Five Takeaways from Warsh’s Press Conference
1. Fed Held Rates Steady, But Two Officials Wanted an Increase.
Warsh had said he wanted “a good family fight” discussion and that’s exactly what he got during the two-day FOMC meetings this week. The Federal Reserve voted to leave its benchmark interest rate unchanged at 3.75% to 4%, with two officials dissenting in favor of a quarter-point increase. Governor Lisa Cook and Cleveland Fed President Beth Hammack argued for higher rates, reflecting concern that inflation remains too high.
In remarks, Warsh pointed to stronger economic activity. U.S. first-half GDP growth was revised up from 1.8% to 2.4%, adding that growth appeared to have accelerated further in the third quarter. Consumer spending was likely expanding at more than 3%, while business investment was running at roughly a double-digit pace.
Investment has also spread beyond technology. High-tech spending remains a leading force, but capital expenditures are broadening across the economy and account for a historically high share of GDP. The labor market has remained firm, with the unemployment rate lower than a year earlier, payroll growth above last year’s pace and jobless claims still low.
The decision to hold rates leaves the Fed weighing an economy that is showing few signs of a sharp slowdown against inflation that has remained above target for nearly six years. Warsh did not signal whether the committee would raise rates at its next meeting, saying policymakers needed more information before deciding on the appropriate policy stance.
2. AI investment Boom is Not Shielded from Interest Rates
Warsh was direct about the relationship between monetary policy and the surge in artificial intelligence investment: “Interest rates get in the cracks.”
The comment pushes back against the idea that spending on AI infrastructure can be treated separately from the cost of capital. Technology investment has helped drive business spending, but Warsh said capital markets were becoming more discerning. Financial conditions have tightened somewhat since September, and credit spreads have widened for some assets.
The implications extend beyond technology companies. Investments in data centers, computing infrastructure and other AI-related projects depend on financing costs, expected returns and investors’ willingness to fund new capacity. Warsh’s position is that monetary policy continues to affect those decisions, even as AI reshapes the outlook for productivity and growth.
That connection is also part of the Fed’s broader review. One of the five task forces is examining productivity and jobs, including the economic effects of new general-purpose technologies such as artificial intelligence. The review will consider how those changes should inform the Fed’s assessment of the economy.
3. Higher energy prices are complicating the inflation fight.
Warsh said inflation remains above the Fed’s 2% objective, while recent increases in energy prices and geopolitical developments have added pressure. Longer-term inflation expectations remain largely anchored, he said, but households’ near-term expectations have risen as energy costs increase.
For the Fed, the concern is whether higher energy prices remain a temporary shock or begin to feed into broader price increases. The central bank must assess that risk while considering evidence that consumer spending and business investment remain strong.
The rate decision also showed that policymakers do not share a single view of the risks. Cook and Hammack favored an increase, while the majority voted to hold rates steady and gather more information. Warsh declined to prejudge the next meeting, leaving the committee’s next move open.
4. Warsh Reinterates His Aversion to Routine Forward Guidance
From his first press conference, Warsh has been changing the way the Fed communicates its decisions. He has argued against routinely signaling the likely direction of interest rates when policymakers cannot know how the economy will evolve. Instead, he wants decisions to be based on the information available at each meeting.
The approach is a departure from a practice the Fed has used for years to help markets anticipate policy moves. Forward guidance can offer investors and businesses greater clarity about the central bank’s intentions, but it can also make it harder for policymakers to change course when economic conditions shift.
Warsh’s preference is for a shorter, more direct explanation of the Fed’s decisions, without committing the committee to a future path. He has also declined to provide his own projections in the format used for the Fed’s quarterly economic forecasts.
The June task forces put that approach into a broader review. The communications group is examining how the Fed conveys its deliberations and decisions; another is reviewing the costs and implications of its balance-sheet regime. The other groups are looking at the quality and timeliness of economic data, productivity and employment, and the Fed’s framework for understanding and responding to inflation.
5. Future Fed Meetings to Devote Time to Strategy, Not Interest Rates
Warsh’s plan to reserve meetings for longer-term policy discussions is the most concrete change announced at this week’s press conference.
The FOMC will continue to meet eight times annually. In 2027, however, one meeting will be devoted to broad monetary policy strategy, with no vote on the federal funds rate and no policy statement anticipated. Warsh expects two such meetings in 2028, leaving six meetings for policy decisions.
Warsh said the committee needs regular opportunities to assess near-term developments, but also time to consider broader questions and longer horizons. Details of what the Fed will disclose after strategy meetings remain under discussion.
The change gives the committee a dedicated setting to examine the assumptions behind its decisions, rather than limiting those discussions to meetings that also determine interest rates. It also formalizes the wider review launched in June, which covers the Fed’s tools, data and policy framework.
The new format will not prevent the Fed from changing rates outside its scheduled decision meetings if circumstances require it. But it will reduce the number of regularly scheduled meetings at which the committee votes on rates—from eight to seven in 2027 and six in 2028.
